If you look at your monthly mortgage statement, you will see it includes Principal and Interest (P&I). But it likely also includes a third component called "Escrow." For many first-time homebuyers, the escrow account is a mysterious black box where money goes, never to be seen again. In reality, it is a highly regulated, legally required financial tool designed to protect both you and your lender. Understanding how escrow works is essential for managing your monthly budget and avoiding surprise payment increases.
An escrow account is a special savings account managed by your mortgage lender. When you buy a home, you are responsible for paying property taxes to your local government and homeowners insurance to your insurance company. These are often calculated alongside your closing costs. These are massive bills that usually arrive once or twice a year.
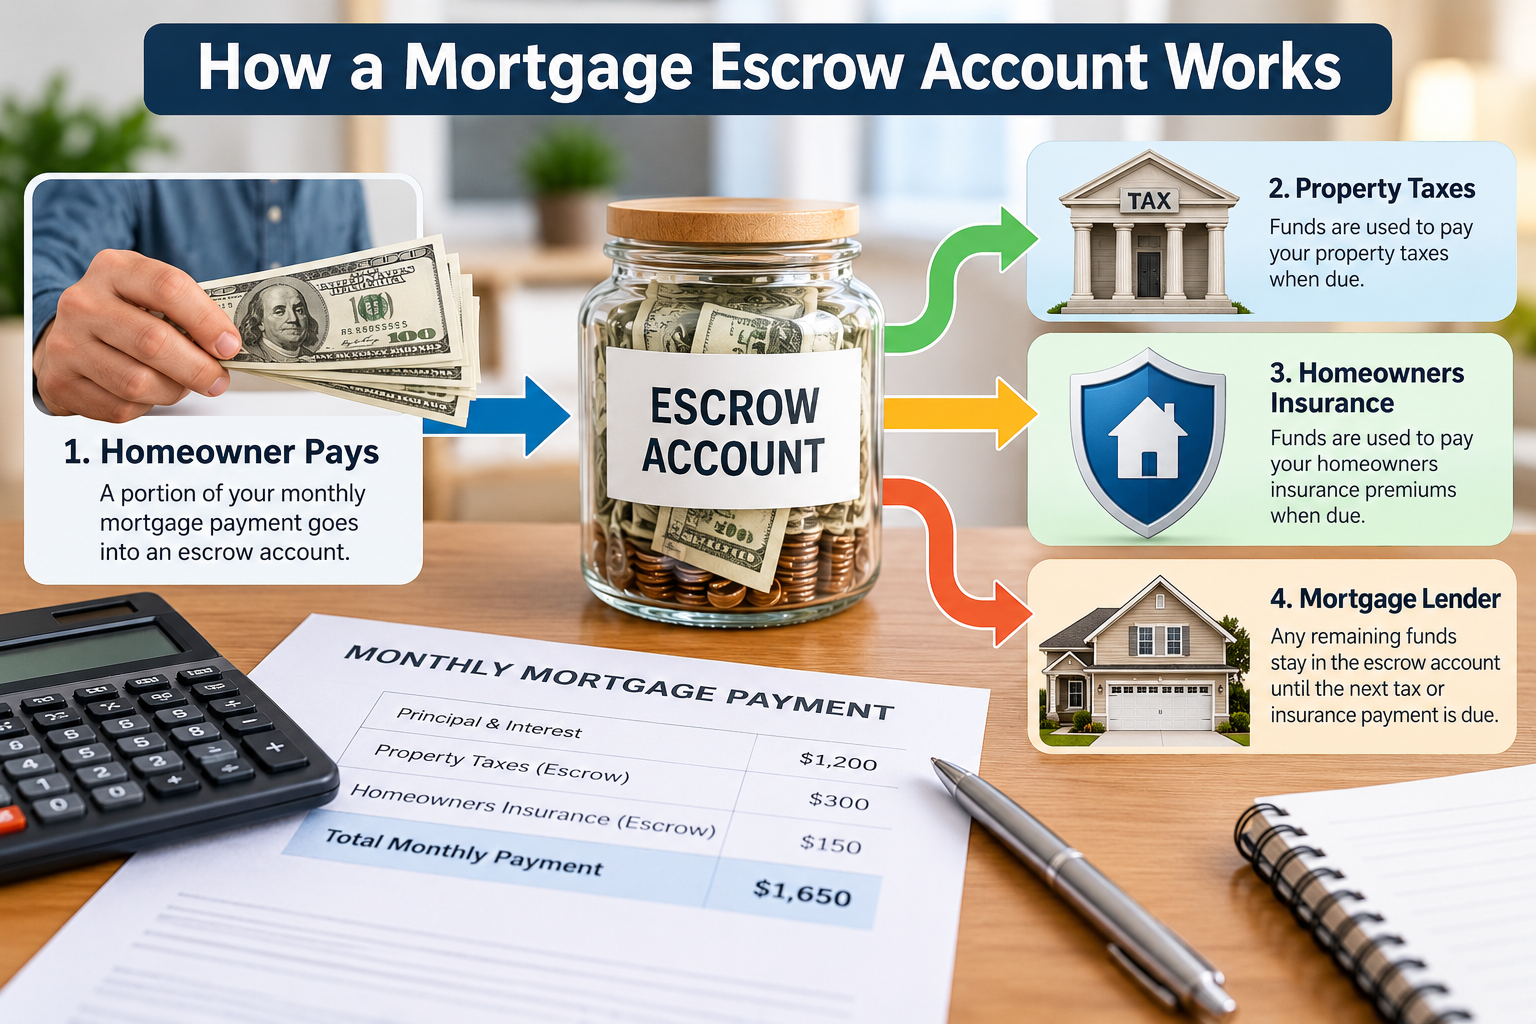
If you had to pay the full property tax bill out of pocket every November, it would cost you thousands of dollars at once. Most people cannot easily budget for that. To make it easier, your lender divides the total annual cost of your taxes and insurance by 12, and adds that amount to your monthly mortgage payment. That money sits in your escrow account. When the tax or insurance bill comes due, the lender uses the escrow funds to pay it on your behalf. This ensures the taxes and insurance are always paid on time, which protects the lender's investment in your home.
To understand your true monthly payment, you need to understand the PITI breakdown (Principal, Interest, Taxes, and Insurance).
The "Taxes" and "Insurance" portions of your PITI payment are the only parts that go into escrow. Principal and Interest go directly to the lender.
This is the most common question homebuyers ask after their first year. You might receive a letter from your lender stating that your monthly payment is increasing by $100. This is called an "escrow shortage."
Escrow payments are based on estimates. The lender estimates how much your taxes and insurance will cost for the upcoming year. However, property tax rates can increase as home values rise, and insurance premiums often increase due to inflation or weather events. If your actual tax or insurance bill comes in higher than the lender estimated, your escrow account will be short on funds.
To fix this, the lender is legally required to adjust your monthly payment upward for the following year to cover the new higher bills, and they may also require you to pay back the shortage over the next 12 months. This can cause a sudden, painful spike in your monthly payment.
You might wonder why your lender wants you to keep extra money in the escrow account. Federal law (the Real Estate Settlement Procedures Act, or RESPA) allows lenders to keep a "cushion" of no more than two months of tax and insurance payments in your escrow account. This cushion protects the lender if a tax bill suddenly increases before the next payment is due.
At the end of the year, your lender is required to perform an escrow analysis. If you have more than two months' worth of payments in the account, the lender must refund the surplus to you within 30 days. If you are short, you will have to pay the difference.
Sometimes, if you have a conventional loan and put down at least 20%, you can request to waive the escrow account. This means you would pay your property taxes and insurance directly yourself. However, many lenders charge a "waiver fee" (often 0.25% of the loan amount) to remove escrow, and they may require a higher interest rate. For most buyers, having escrow is actually a helpful budgeting tool, because it forces you to save for large bills month by month.
To avoid escrow surprises, you should review your escrow statement carefully each year. Check the estimated tax and insurance amounts against your actual bills. If you believe the lender's estimate is too high, you can dispute it. You can also shop around for cheaper homeowners insurance, which will lower your escrow payment for the following year. If you have questions about your escrow statement, contact your lender's escrow department directly. They are required to explain the numbers to you.
Use our mortgage calculator to include taxes and insurance in your monthly payment estimate, so you are never caught off guard.